
You open the appraisal district's envelope, see a higher property value, and immediately wonder how much more you'll owe. Before you reach for a tax calculator, check the property details and the protest instructions. The most useful question isn't just whether the increase looks steep. It's whether the district can support the value using accurate records and comparable evidence.
A Notice of Appraised Value in Texas is a deadline-driven opportunity to check that work. For homeowners in Austin and Travis County, rental owners, and commercial property managers, the right response is the same: preserve the notice, verify the facts, and decide promptly whether there's something worth challenging.
What Your Notice Says and What to Check
The Notice of Appraised Value is the appraisal district's written proposal of the value it plans to place on your property for the tax year, sent when that value increases from the prior year. It isn't a demand for payment. Treat it as a working document you can test against your deed, property records, exemption paperwork, and market evidence.
Notice fields and what to check
| Notice field | What it tells you | What to check |
|---|---|---|
| Account or property ID | Identifies the parcel on the district roll | Matches your deed, tax statement and mailing address |
| Property address and legal description | Confirms which land and structure are assessed | Lot, acreage and street address are correct |
| Prior-year appraised value | Baseline for this year's change | Compare the gap; a large jump needs a reason |
| Current appraised value | The district's proposed value | Check it against recent comparable sales |
| Market value | Estimated value used for tax purposes | Should be in line with similar properties |
| Exemptions listed | Reductions already applied | Homestead, Over-65, disabled and other exemptions appear if you qualify |
| Land and improvement split | Value of the lot versus the buildings | Verify acreage and how the land is actually used |
| Square footage and property class | Size and use category used in the calculation | Confirm living area and whether rental or commercial use is recorded correctly |
| Protest deadline and hearing details | When and how to file a protest | Mark the date and note the informal conference option |
Match the parcel before judging the price
Start with the account or property ID, especially if you own adjoining lots or multiple rentals. Reconcile it with your tax statement and ownership documents, then check the mailing address separately so future correspondence reaches you.
Read the street address and legal description together. A street address may look familiar while the recorded lot, acreage, or parcel boundaries need correction; a deed, plat, or survey gives you something concrete to compare.
Put the prior-year and current appraised values side by side. A large difference calls for an explanation, not an automatic conclusion that the district is wrong. Compare the market value separately with sales of similar properties.
Check the assumptions behind the value
Review every exemption entry against your eligibility and application records. A missing exemption is a different problem from an excessive market estimate, so keep the supporting documents separate.
For the land and improvement split, confirm the acreage and actual land use. For square footage and property class, compare the district's description with a floor plan, measurements, and documents showing how you use the property; a garage shouldn't become living area just because the record is unclear.
Finally, locate the protest instructions, hearing information, and informal conference option. Copy every printed figure into a comparison sheet before doing anything else, keeping the original notice unchanged so you can track exactly what you're challenging.
How Texas Appraisers Set Your Value
Think of market value as the property's likely price tag in an ordinary sale, and appraised value as the value carried into the property-tax calculation after applicable appraisal limitations. They can match, but they don't have to. Neither should be confused with taxable value, which reflects applicable exemptions.
For a clearly hypothetical example, suppose a home has a $400,000 market value and a $380,000 appraised value. Applicable exemptions would then reduce the taxable base before local rates are applied. Those figures illustrate the calculation sequence, not a promised exemption or a prediction of the bill.
Understand the valuation method
Appraisal districts use mass appraisal to evaluate groups of properties. The practical question is whether the method and the underlying inputs fit yours.
- Sales comparison: Appraisers compare sales of similar properties, accounting for meaningful differences in size, location, and condition. A nearby renovated home isn't automatically a good match for a property needing substantial work.
- Cost approach: Appraisers consider the land and the cost of improvements, allowing for depreciation. Check whether the building description and condition assumptions are realistic.
- Income approach: For rental or commercial property, appraisers examine income-producing capacity. Rent, vacancy, operating expenses, and the property's actual condition become important evidence.
Our explanation of property valuation methodology gives owners more context for judging which inputs deserve attention.
Separate value from the eventual bill
The appraisal district determines value; schools, cities, counties, and other taxing units set their respective tax rates. A valuation protest should therefore address the property's value or another appealable appraisal action, not dissatisfaction with a taxing unit's budget.
Annual changes may reflect market trends, new improvements, corrected records, or mistakes. Ask the district what changed before assuming the increase represents an equivalent change in what a buyer would pay.
Practical rule: Challenge the assumption you can disprove, not simply the number you dislike.
The notice is a proposal, not your final property-tax bill.
Caps, Exemptions and the 2027 Sunset Risk
A cap can limit the appraised value used for some tax calculations, while an exemption reduces the taxable value for an eligible property. Neither makes an incorrect market value correct, and a cap does not set a limit on the tax bill.
The Texas Comptroller's property valuation guidance explains that the 10% homestead cap applies to a qualifying residence homestead beginning January 1 of the year after the owner qualifies. It generally limits the increase in appraised value to 10% over the prior appraised value, plus the market value of new improvements. A separate, temporary 20% circuit-breaker limitation applies to many non-homestead properties for tax years 2024 through 2026. Its scheduled expiration could expose eligible properties to larger increases in 2027 if the limitation is not extended.
Appraisal limits and their status
| Limit | Applies to | How it works | Status |
|---|---|---|---|
| 10% homestead cap | Qualifying residence homestead | Prior appraised value plus up to 10%, plus the market value of new improvements | Ongoing; starts January 1 after the owner qualifies |
| 20% circuit-breaker limit | Many non-homestead properties, including qualifying rentals and commercial property | Limits annual appraisal increases, subject to eligibility rules and adjustments | Applies to tax years 2024 to 2026; scheduled to expire afterward unless extended |
| New improvements | Property with added construction | Market value of qualifying new improvements is added outside the applicable capped increase | Accounted for in the year the improvement is added |
A cap doesn't settle whether the value is correct
The homestead limitation applies to appraised value, not the tax bill. Tax rates and exemptions affect the eventual amount due, so review the market value and property record separately from any capped value.
A buyer should not assume the seller's appraisal treatment carries over unchanged. Check whether the property qualifies and confirm the ownership details relevant to the limitation. The guide to Texas homestead laws explains protections and qualifications homeowners should review.
Plan for the scheduled sunset
For an investment property, keep the current market value, appraised value, exemption status, and limitation information together. Model how the taxable base could change if the temporary limitation ends, rather than assuming recent capped increases will continue.
Treat that calculation as a planning scenario, not a forecast or tax quote. Confirm the current status of the limitation and whether the property qualifies. Ownership changes and added construction can also affect the calculation.
Key Dates for Protesting Your Appraisal
Texas uses different notice schedules for different property types. Under the Texas Comptroller's protest guidance, single-family residences, including homesteads, generally receive notices by April 1, and other property, including commercial, multifamily, and many investment properties, by May 1, or as soon afterward as practicable; the ordinary protest deadline is May 15 or 30 days after mailing, whichever is later.
Keep the distinction between a notice target date and your filing deadline clear. A later notice doesn't mean you should use the usual spring deadline without checking the mailing date.
The timeline highlights the different notice schedules.
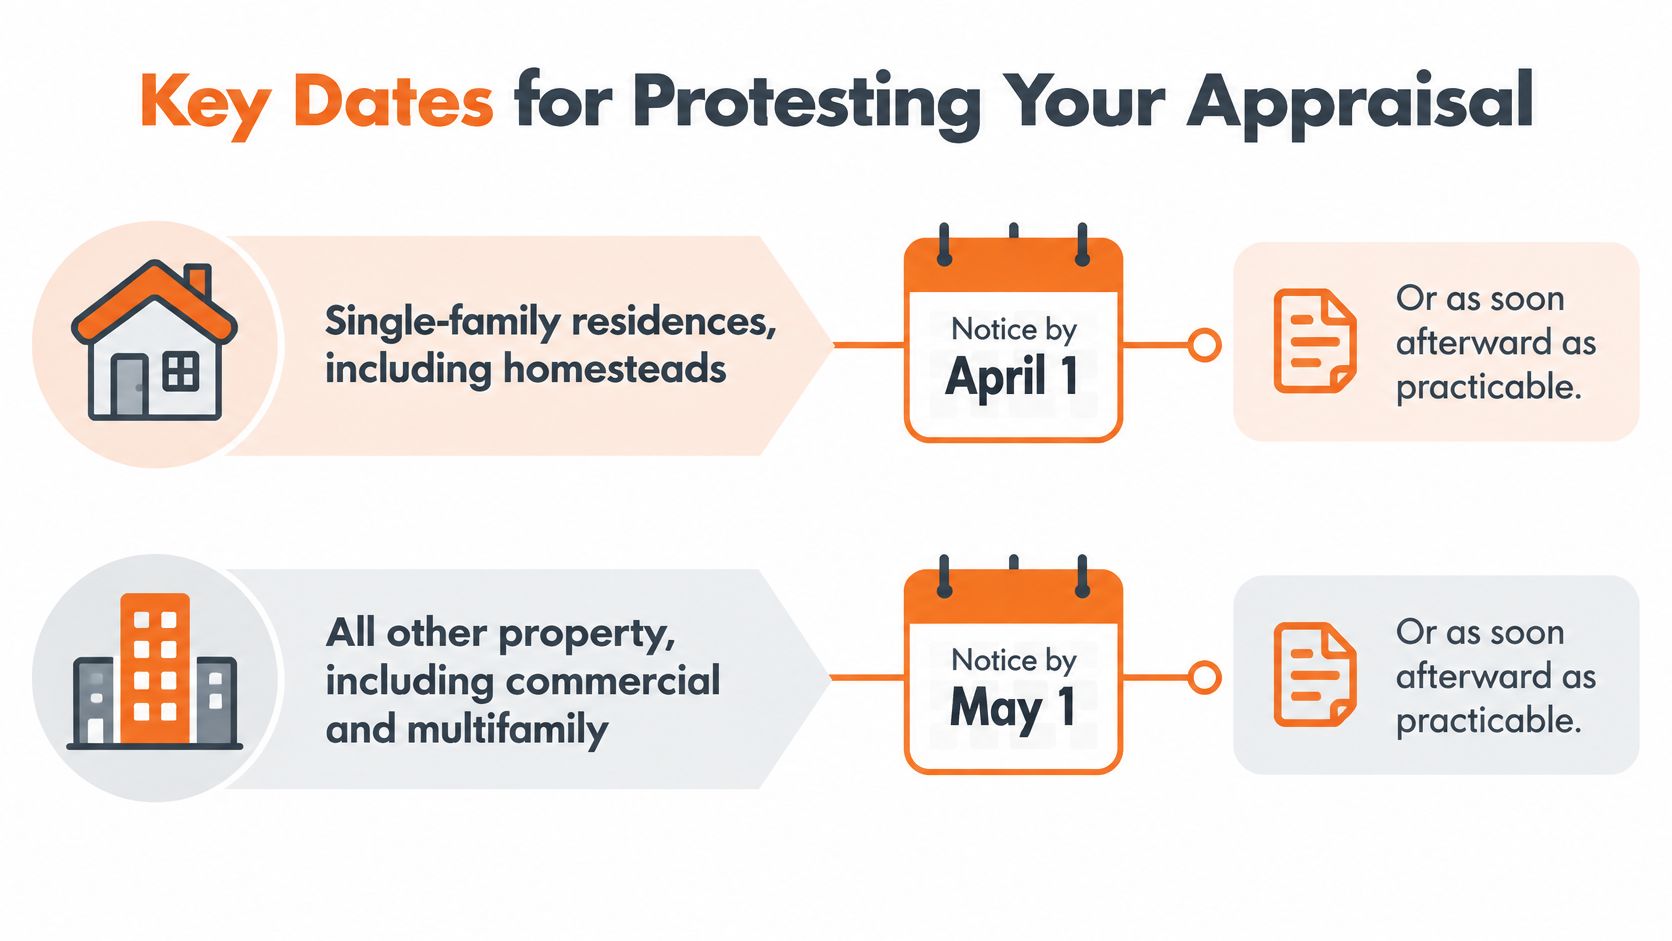
Notice and protest dates for Texas owners
| Event | Typical date | Rule to know |
|---|---|---|
| Notice to single-family residence | By April 1 | Or as soon afterward as practicable |
| Notice to other property | By May 1 | Includes commercial, multifamily and many investment properties; or as soon afterward as practicable |
| Protest deadline | May 15 or 30 days after mailing | Whichever is later; counted from the mailing date |
| ARB hearings begin | After May 15 | Protests are heard by the appraisal review board |
| Most ARB hearings finish | By July 20 | Larger counties may extend the completion date |
Count from mailing, not delivery
Save the envelope, postmark, and any electronic notice record. The mailing date starts the count, not the day you open the envelope or first notice the new value online.
For a hypothetical application of that rule, a notice mailed April 20 produces a May 20 protest deadline because the mailing-based period ends later than the ordinary deadline. Don't substitute your delivery date in that calculation.
Use the property tax protest deadline guide alongside the instructions on your notice. If the printed deadline and your calculation differ, contact the district promptly and preserve its response.
Calendar the filing before preparing the whole case
The notice arrives before local tax rates are applied, but your opportunity to challenge the underlying appraisal is already running. Waiting for a tax bill is the wrong sequence.
- Record the deadline: Put it on your calendar the day the notice arrives.
- Identify the filing method: Check the district's instructions for its portal, form, or other accepted submission process.
- Keep proof: Save the filing confirmation and every document you submit.
Don't postpone a timely filing while searching for the perfect comparable sale. Protect the filing opportunity, then organize the supporting evidence around the issues you've identified.
What to Do With a Late or Missing Notice
You discover the higher value while checking your account and assume the protest window has closed. That conclusion may be premature. Late delivery, a missed ordinary deadline, and failure to send a required notice are different situations, with different questions to resolve.
Start by asking the district when it mailed the notice, where it sent it, and whether the appraisal records have been approved. Preserve the answers rather than relying on a phone conversation alone.
Good cause and required-notice failures
The Texas Comptroller's protest procedures explain that a late protest may be possible for good cause before the appraisal records are approved; when a required notice wasn't sent, a separate route may generally remain available until the day before taxes become delinquent or, subject to statutory conditions, within 125 days after receiving a tax bill.
For good cause, document the circumstances that prevented timely filing and when you first learned of the problem. Approval of the appraisal records matters, so ask about that status immediately.
For a required-notice failure, identify which notice should have been sent and the facts supporting your claim. Not remembering an envelope isn't the same as establishing that the district failed to provide required notice, and relief isn't automatic.
Build a record of nonreceipt
Collect a concise, dated file:
- Write the timeline. State when you expected the notice, when you first saw the proposed value, and how you discovered it.
- Preserve the address record. Save the mailing address shown in the district's account, including any address-change correspondence.
- Keep the mail evidence. Retain returned mail, envelopes, postmarks, or electronic delivery records.
- Identify the triggering bill. Save the taxing-unit bill that alerted you to the issue and record when you received it.
Ask the district or ARB which procedure applies, what submission it requires, and how you can document the filing. Keep copies of the request and response.
A missed notice isn't automatically a missed appeal, but an available remedy can still have a firm cutoff.
Act within days rather than letting the issue sit for weeks. A consultant can help distinguish an ordinary filing question from a late-protest or required-notice claim before you spend time assembling evidence for the wrong route.
Common Errors to Spot on Your Notice
A proposed value that exceeds recent comparable sales is an important place to start. You don't need a falling market to have an excessive appraisal: the district may have compared your property with better-condition buildings, larger homes, or more desirable locations.
The Texas Comptroller's appraisal protest guidance identifies valuation errors, omitted exemptions, incorrect square footage, and misclassification as issues that can support an evidence-based protest independently of whether the market declined. Compare the notice with the prior-year record, actual sales, and the district's current property description, not just with your reaction to the increase.
Use this checklist to identify the type of problem before collecting documents.
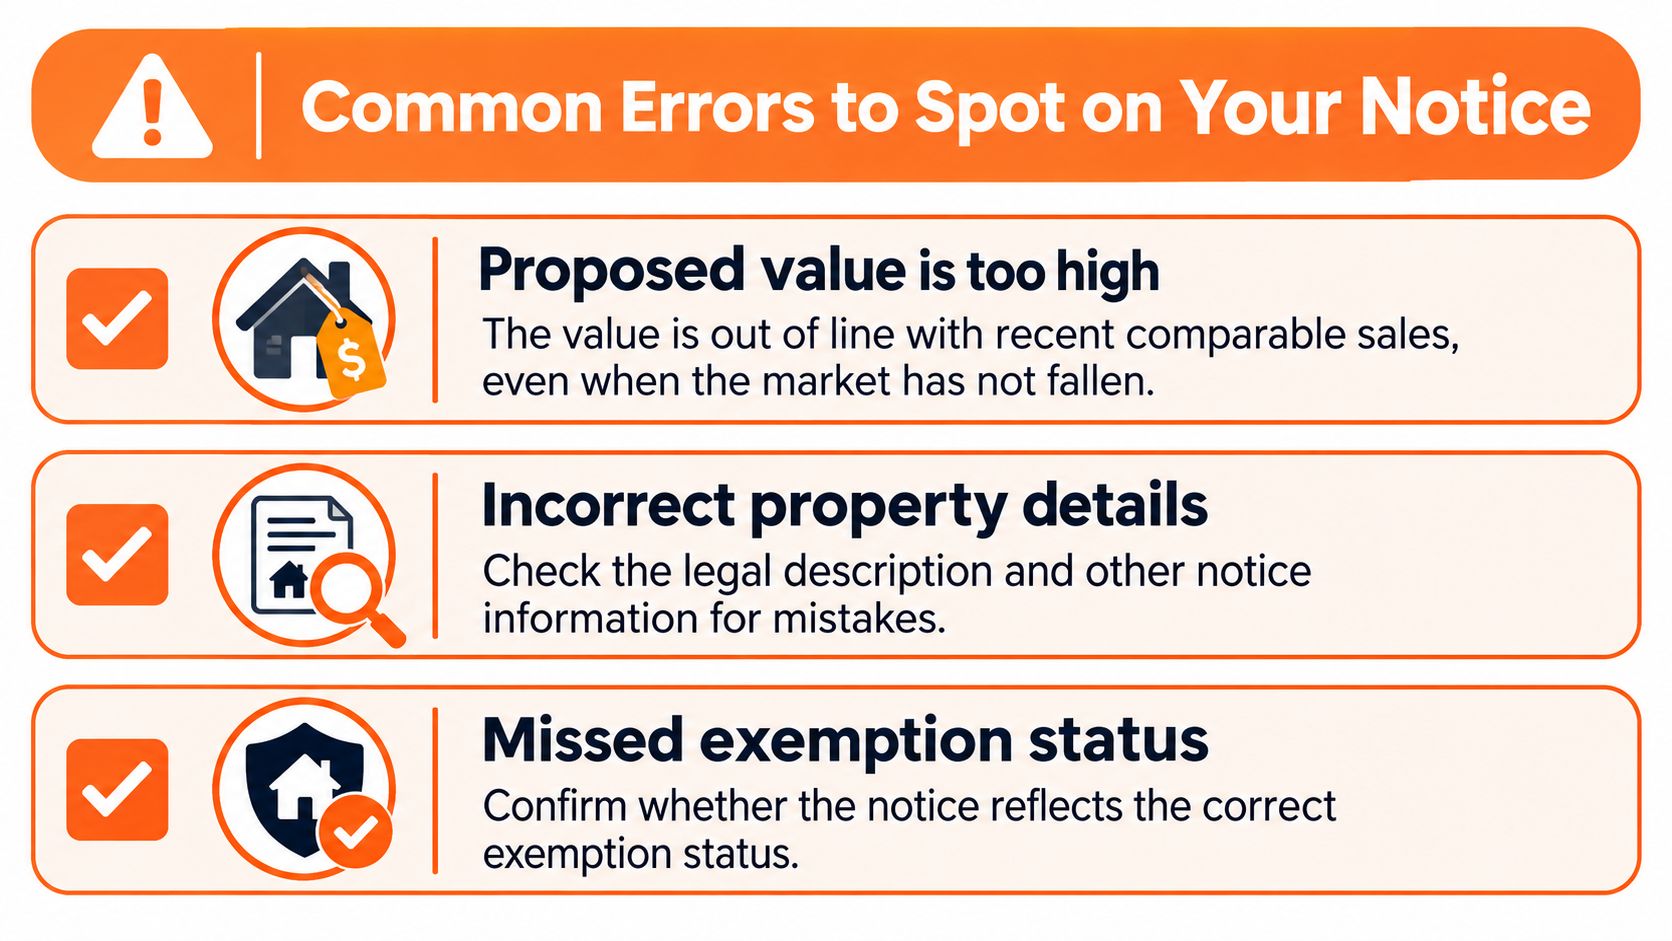
Common notice errors and how to verify them
| Error | Verify against | Evidence to gather |
|---|---|---|
| Value out of line with comparable sales | Recent arm's-length sales of similar property | Sales list adjusted for condition, size and location |
| Omitted exemption, such as homestead, Over-65 or disabled | Exemptions line on the notice | Proof that you qualify for the exemption |
| Incorrect square footage | Living area on the notice | Measurements or floor plan checked against the property record |
| Misclassified property, such as rental use recorded incorrectly | Property class and use on the notice | Lease or rent records showing actual use |
| Wrong acreage or legal description | Land and legal description on the notice | Deed, plat or survey that matches the parcel |
Turn a suspected error into a verifiable issue
For a value gap, screen comparable sales before calculating an average. Exclude properties that differ materially, or explain adjustments rather than treating every nearby sale as interchangeable.
For an omitted exemption, verify eligibility and the district's application record. An exemption shown last year is useful background, but your current qualification and paperwork are what need checking.
For square footage, distinguish living area from garages, patios, and other spaces. Submit a clear floor plan or measurements that explain the discrepancy, rather than a competing total.
Check use and parcel boundaries carefully
For classification, don't assume a residential building stops being residential property because you lease it. Verify the particular class or use entry that's wrong and show why the distinction affects the appraisal or exemption treatment.
For acreage or legal-description errors, match the district's parcel to the deed, plat, or survey. Make sure your evidence identifies the same property rather than a neighboring tract or an earlier parcel configuration.
List every suspected error in a single issue log, with a column for supporting evidence and another for unresolved questions. Then prioritize the strongest, best-documented issues instead of presenting a long collection of unsupported objections.
Building Evidence for a Protest Hearing
A hearing packet should make the requested correction clear and easy to check. The Texas Comptroller's appraisal-notice guide describes the Property Owner's Notice of Protest and the option to meet informally before a formal ARB hearing.
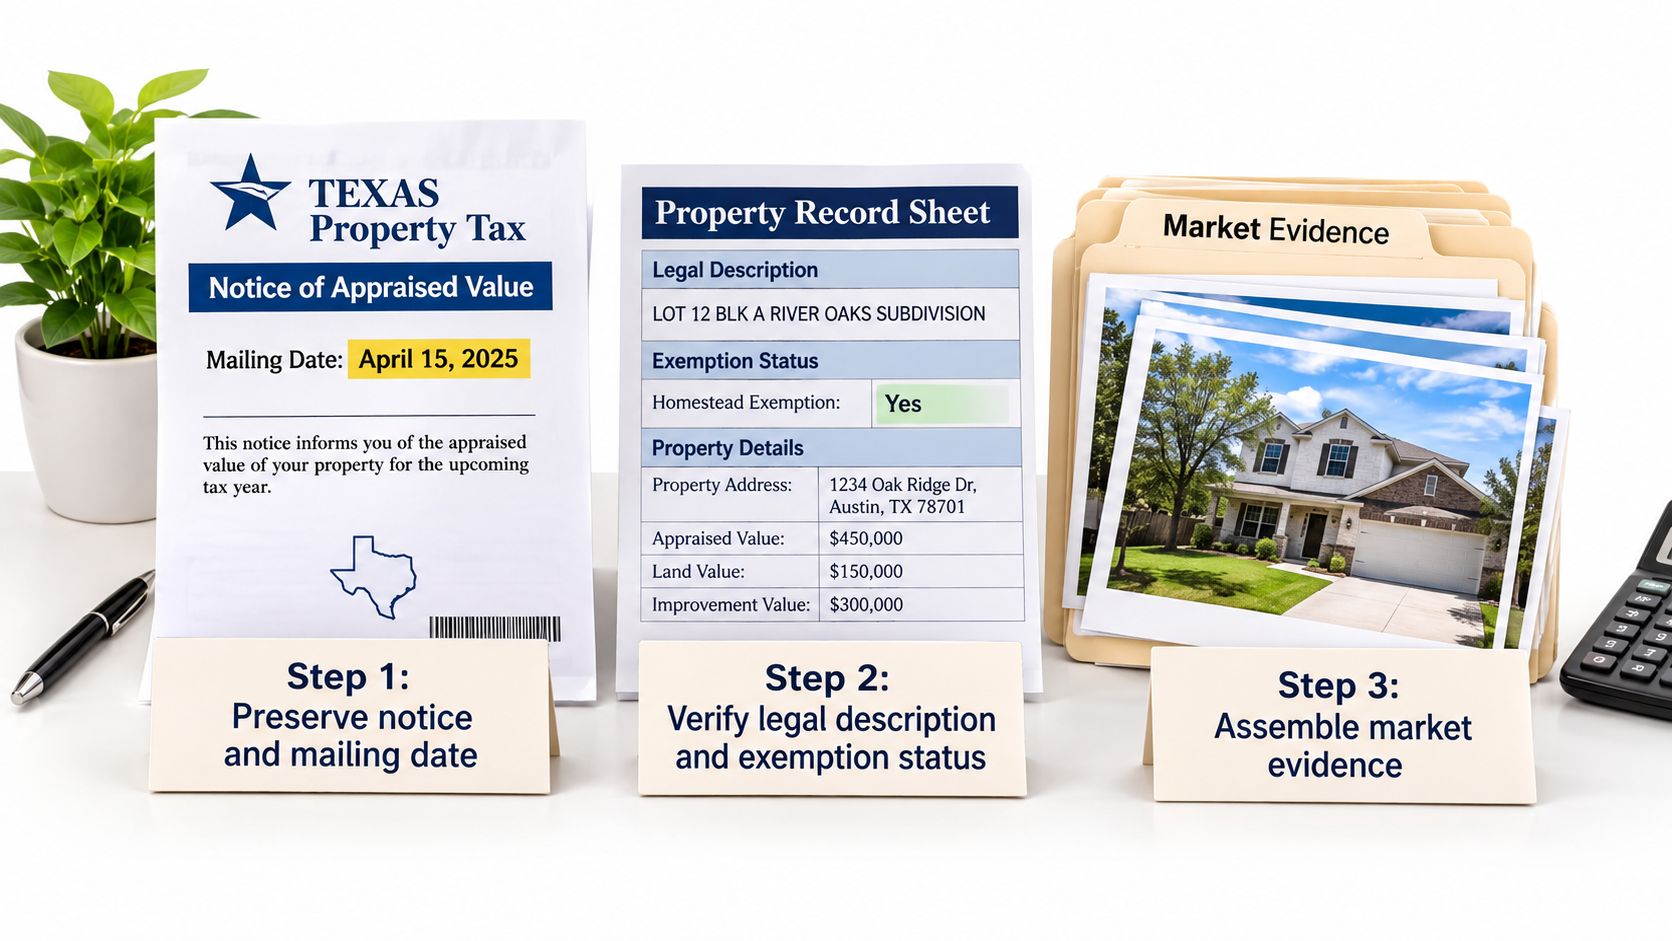
Preserve, verify, then support the correction
Keep the notice and mailing record together. Save the notice, envelope, filing confirmation, and correspondence in one folder. Use clear file names so you can find each item during a conference.
Check the parcel and exemption details. Compare the legal description and exemption status with the appraisal district's account. If the notice arrived late or did not arrive, address filing eligibility through the applicable procedure; supporting evidence alone does not resolve that question.
Match each piece of evidence to your claim. For a market-value protest, use comparable sales and explain adjustments for differences in condition, size, and location. Dated photographs and repair bids can support a claim that a property's condition affects its value.
For income-producing property, organize income and expense statements, rent records, and condition documents. For an unequal-appraisal claim, identify comparable properties and explain why their appraisal treatment supports your requested correction. A lower value for an unrelated property is weak evidence.
Choose the right level of help
- Self-filed protest: You manage the filing, evidence, scheduling, and presentation yourself, with no representative fee.
- Informal conference: A focused discussion with district staff may resolve a clear factual discrepancy before a formal hearing. It does not replace meeting the filing deadline.
- Formal hearing representation: A representative handles preparation and presentation, which can help when the valuation or supporting records are complicated. Representation has a cost, so weigh that against the time and work involved in handling the case yourself.
INTELLI's Assessment Appeals service challenges inflated property valuations with evidence and expert representation. It handles documentation gathering, deadline management, and representation at hearings.
This video provides another format for reviewing the process.
Before the hearing, check that your packet includes the notice, mailing record, comparable sales, photographs, repair bids, relevant income records, and exemption proof. State the correction you are requesting, then connect each document to the reason for it.
Decide Whether to File Before the Deadline
A notice puts a decision on the calendar, but it does not decide whether your value is correct. Check the filing deadline promptly, then weigh the disputed entry against the evidence you can provide.
Start by confirming the notice's mailing information, protest deadline, and hearing instructions. If the notice arrived late or did not arrive, investigate whether a filing route remains available rather than assuming the opportunity has passed. Calendar the filing, evidence preparation, and hearing separately.
Choose whether to file on your own, seek an informal resolution, or appoint a representative. The Texas Comptroller's taxpayer remedies guide explains that the appraisal review board hears appraisal protests, while taxing units set tax rates. Keep the requested correction tied to value, exemptions, or another applicable appraisal action.
Decision test: Can you identify the disputed entry, explain why it is wrong, and support a specific correction?
INTELLI uses a proprietary, data-driven system to prepare evidence for notices, deadlines, exemptions, and valuation challenges. It handles property evaluation, documentation gathering, deadline management, and representation at hearings.
To explore potential savings, enter your property street address on INTELLI's homepage form or call 512-987-6543. Review the engagement terms in writing, and act promptly so there is time to prepare a supported challenge.